
Home Insurance for Avalon Beach and Bay Homes
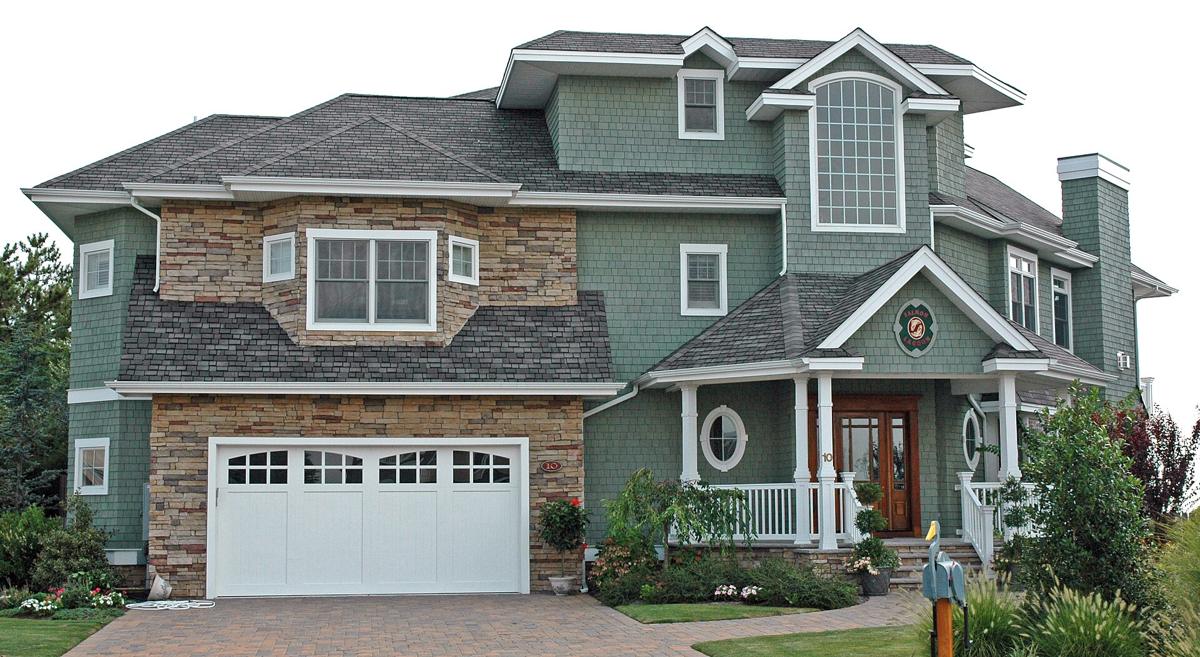
Most Avalon homes are second homes, many rebuilt in the last twenty years as large elevated houses with garages and decks underneath. Insuring one well means getting the rebuild cost, the wind deductible and the months it sits empty right.

Written and reviewed by Nate Feuerman, Stonebrook Insurance
Updated
To speak with an insurance advisor now, callCall an insurance advisor at (732) 905-4100Monday–Friday, 9 a.m.–5 p.m.
We’re closed right now. Leave your number and an advisor will call you back the next business morning.
Short answers
Is an Avalon summer home insured like a primary home?
No. Carriers write it as a seasonal or secondary home and ask how long it’s occupied.
What’s a hurricane deductible?
A separate deductible for named-storm wind damage, usually 1% to 5% of the dwelling limit.
Is my home covered if I rent it out?
Only if the policy allows it. Tell us how often you rent.
Do I need a high-net-worth carrier?
For most Avalon homes, they offer better coverage and often better value.
Avalon homes, and what each needs.
New Elevated Homes
Large custom homes built on pilings, with parking and storage below. Rebuild cost, wind and flood below the living floor.
Oceanfront Blocks
The most valuable homes, behind the dunes. Surge, wind and salt air.
Bay-side Homes
Homes on the back bay, with docks. Bay flooding comes more often than ocean flooding.
Older Cottages and Duplexes
Smaller homes, many due for replacement. Older systems and lower elevation.
What causes claims in Avalon homes.
Hurricanes and Nor’easters
Wind deductibles apply; roofs, decks and windows take the hit.
Empty in Winter
Frozen pipes cause many of the biggest second-home claims.
Renters
Guests and tenants add liability and wear.
Salt Air
Corrodes HVAC and metal fittings.
High Rebuild Cost
Custom construction on pilings costs far more per square foot.
How we usually set up an Avalon home policy.
| Coverage | Typical policy | What we usually recommend in Avalon |
|---|---|---|
| Dwelling | A fixed limit | Guaranteed or extended replacement cost |
| Wind deductible | Assigned | Chosen on purpose |
| Flood | Separate NFIP policy | NFIP plus excess, or private flood to full value |
| Freeze protection | Conditions apply | Low-temperature alerts and water shut-off |
| Liability | $300,000 | $500,000 plus a large umbrella |
| Carrier | Standard | Private Client carriers |
A checklist for Avalon owners.
- 01
Shut Off and Drain the Water
Or install an automatic shut-off valve.
- 02
Set the Heat and Add Alerts
Low-temperature and leak sensors.
- 03
Line Up a Caretaker
Someone who checks the house after every storm.
- 04
Review Rentals
Make sure the policy allows them.
- 05
Check Your Flood Limits
Large homes need more than the NFIP.
Own a home in Avalon?
We’ll compare high-net-worth carriers and quote flood alongside.
What our clients say.
Five-star reviews from Stonebrook clients on Google.
“Nate and the whole Stonebrook team were great! From the beginning, down to the last minute. It was a breeze working with them. Had great insurance programs for my home, and kept me informed of all my options. They really came through, even on a last minute closing. 10/10 Highly recommended”
“Super quick and easy to deal with. Saved a few hundred dollars on my homeowner's policy, with almost no effort on my end.”
“Stonebrook is the best insurance broker i have worked with. They researched to find me the best policy for the best price while still providing advice on limits my policy should be at. Excellent service!”
More for Avalon homeowners.
What Avalon homeowners ask us.
How much does home insurance cost in Avalon?
It depends on rebuild cost, elevation, construction, distance to the ocean and the carrier. High-net-worth carriers often offer better value for larger homes.
Is my Avalon home covered while empty in winter?
A policy written for a seasonal home is built for it, with conditions about heat and water.
Does homeowners insurance cover flood?
No. Flood needs a separate policy.
Can you insure my boat too?
Yes, with agreed-value hull and named-storm haul-out coverage.
Neighbors: Stone Harbor, Ocean City.
Sources for this page
Figures come from the sources listed and are dated where the source gives a date. Coverage descriptions are general; your policy wording controls.
Let’s discuss how we can protect what you’ve built.
Take 30 seconds to take the first step towards better coverage.
Get a quote.
Tell us what you need and we’ll take it from there.