
Home Insurance in Howell, NJ
Stonebrook is an independent insurance agency, protecting New Jersey homeowners since 1982 from our office in nearby Lakewood. Howell is a 61-square-mile township of farms, woods and suburbs between Lakewood and Wall, with Route 9 running through its center. Here is what matters most for Howell homes. New to home insurance? Start with our home insurance guide.
Reviewed by Nate Feuerman, High Net Worth Insurance Producer at Stonebrook
Updated
Quick answers for Howell homeowners
Is Howell considered coastal for home insurance?
Usually not, but it depends on the address. Most of Howell is 8 to 13 miles from the ocean, while Ramtown and the eastern edge are about 6 miles away, which some carriers count toward wind and hurricane rules.
Do I need flood insurance in Howell?
It is worth considering, because standard homeowners policies exclude flood.
What is a hurricane or wind deductible?
It is a separate, higher deductible for storm damage, usually a percentage of your dwelling limit instead of a flat dollar amount.
How much dwelling coverage should I have in Howell?
As of 2026, we like to see about $250 per square foot of living space as a starting point, and more for custom finishes.
From iron furnace and farm country to a Route 9 suburb.
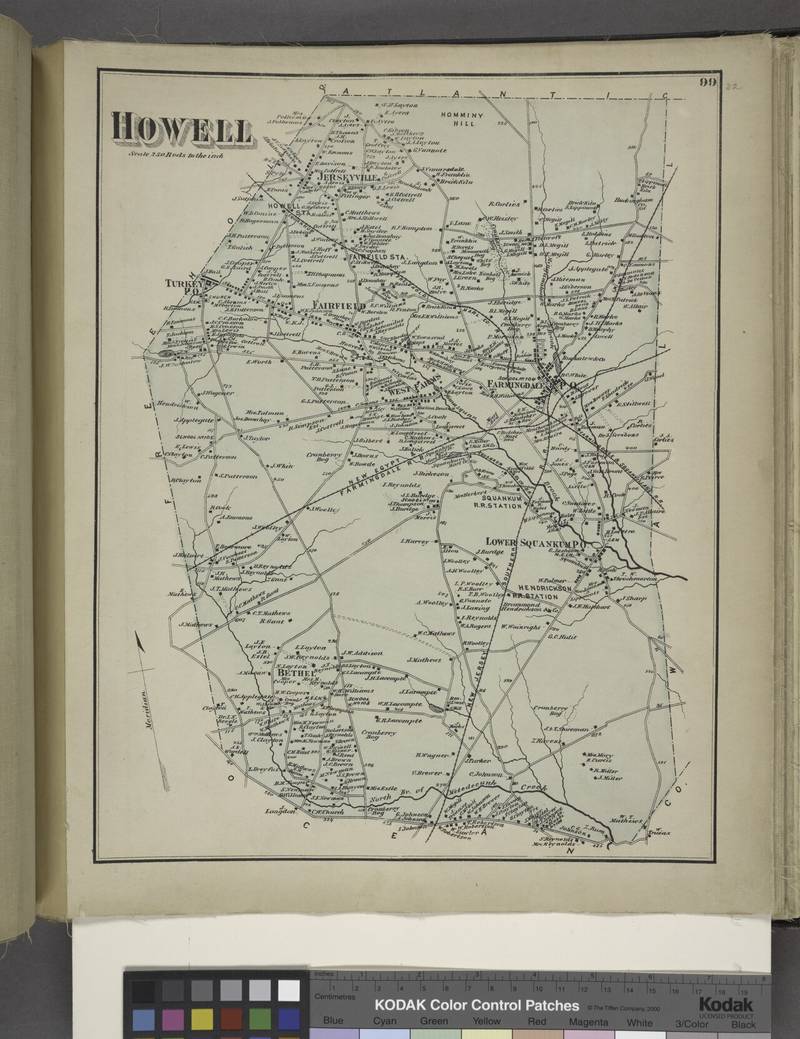
Howell was incorporated on February 23, 1801, from part of Shrewsbury Township, and named for Richard Howell, New Jersey’s third governor (1794–1801). It first reached the ocean, taking in what is now Wall, Brick, Lakewood and the shore from Belmar to Barnegat Inlet. Brick (1850), Wall (1851) and Farmingdale (1903) split off, and in 1929 its southern lands went to Jackson and Lakewood. Benjamin B. Howell’s Monmouth Furnace became the Howell Works, which James P. Allaire bought in 1822 to process bog iron.
For most of its history Howell was farm country, with crossroads villages like Adelphia, Ardena, Jerseyville, Southard, Squankum and West Farms. From 1919, Jewish poultry farmers settled around West Farms and Farmingdale and built a community center in 1928; the egg business faded by the 1960s. In 1907, Arthur Brisbane bought about 5,000 acres for a children’s tuberculosis preventorium that ran until 1960. Its grounds are now the municipal complex on Preventorium Road. Freewood Acres is home to a Kalmyk American community, and St. Alexander Nevsky Russian Orthodox Cathedral dates to 1936.
Today Howell is a bedroom suburb with farms and horse properties still in its western half. It had 51,075 residents in 2010 and 53,537 in 2020, including 6,329 in Ramtown. Route 9 is its commercial spine, and town hall moved there in 2012. In recent years more Orthodox Jewish families from neighboring Lakewood have made Howell their home. The township has two Orthodox high schools, Bais Leah and Yeshiva Emek Hatorah, and a 66,441-square-foot kosher supermarket is planned for the former Stop & Shop at Lanes Mill Marketplace on Route 9.
“We know Howell from Ramtown to Adelphia: farms, wells, oil tanks and all.”
Things to see in Howell.
A four-billion-gallon reservoir, a steam railroad and the Manasquan River.
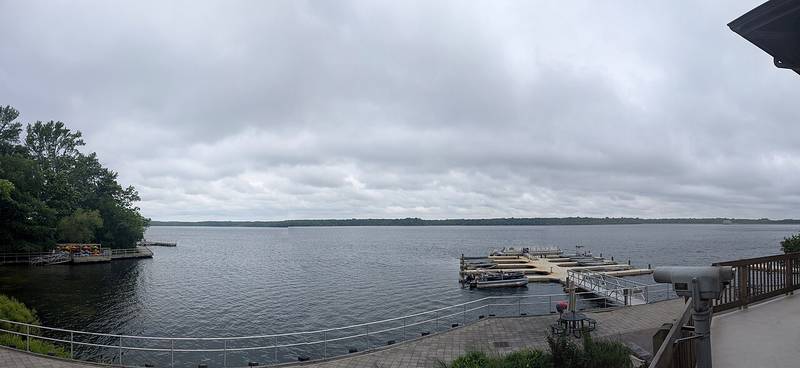
Manasquan Reservoir
A 770-acre reservoir holding about 4 billion gallons, operational since 1990 and run as a Monmouth County park on Windeler Road. A 5.1-mile gravel perimeter trail, kayak and rowboat rentals, year-round fishing and an environmental center; the park draws over a million visitors a year.
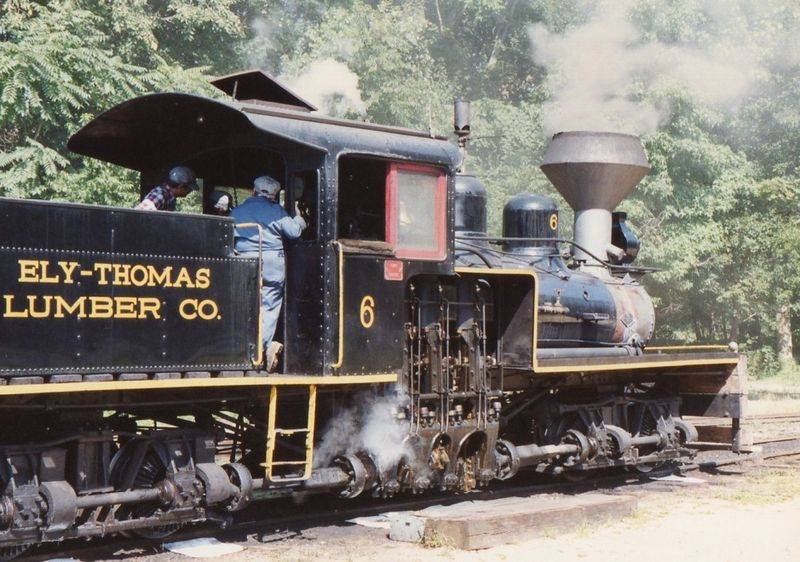
Allaire State Park
3,205 acres in Howell and Wall along the Manasquan River, with trails, a year-round campground and the Pine Creek steam railroad on a half-mile loop. The restored 1820s ironworks village, Allaire Village, sits on the Wall Township side.
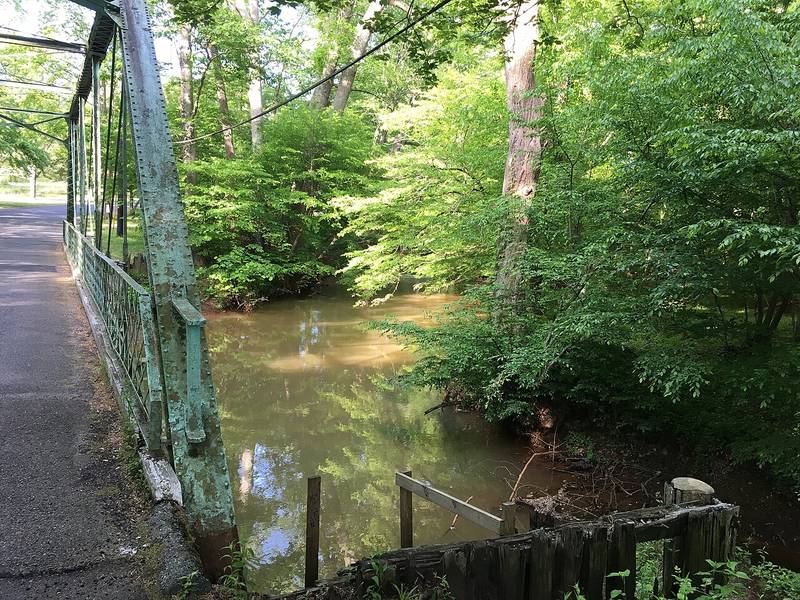
Howell Park Golf Course
An 18-hole, par-72 Monmouth County course opened in 1972, entered over a one-lane bridge across the Manasquan River. It anchors the county’s Manasquan River Greenway with the reservoir.
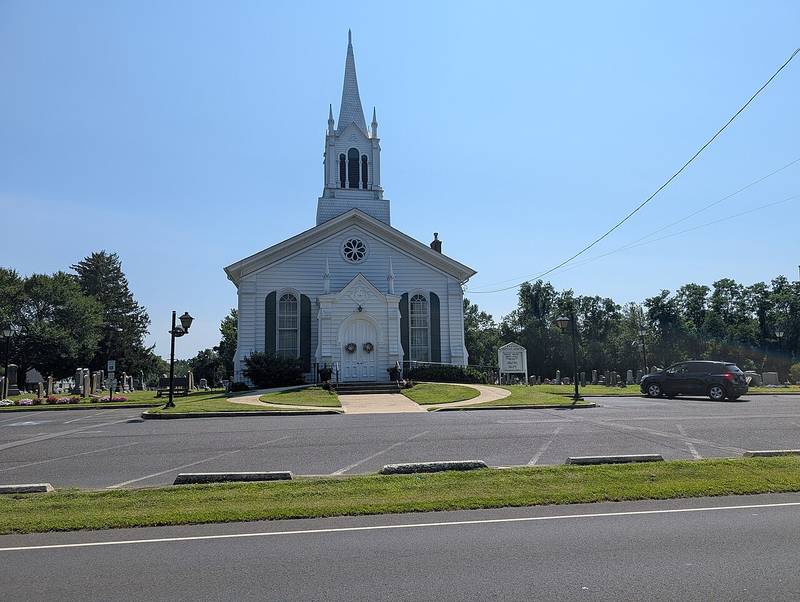
Ardena Baptist Church
A white steepled church and cemetery on Route 524 in Ardena, a crossroads in western Howell. Scenes for the 2005 War of the Worlds were filmed in Howell, and the neighborhood set built at Universal Studios Hollywood is called Ardena Acres.
Alfred C. Sauer Park at Echo Lake
A township park with a fishing and kayak dock, nature trail, pavilion and playground. No swimming. Renamed in 2014 for a local environmentalist.
St. Alexander Nevsky Cathedral
Founded in 1936 at 220 Alexander Avenue. The brick Byzantine Revival cathedral was consecrated in 1997 and is the seat of a Russian Orthodox diocese.
Mackenzie Museum and Library
The former home of William Prickitt, who led the 25th Regiment of U.S. Colored Troops in the Civil War.
Bear Swamp Natural Area
A forested wetland along Maxim-Southard Road that recharges the township’s groundwater.
Howell-specific insurance knowledge.
How close is the coast?
Howell is inland, but its eastern and southern edges are only about 6 miles from the ocean. Ramtown and the Allaire area are roughly 6 miles from the beach at Manasquan and Point Pleasant Beach, while western sections like Adelphia and Ardena are about 12 to 13 miles inland. Some carriers set wind and hurricane deductibles, or limit new policies, by distance to the coast, so a few addresses in eastern Howell may be treated as closer to coastal than the rest of town. It depends on the carrier and the address.
Hurricanes and Sandy
Sandy was no longer a hurricane when it came ashore near Brigantine on October 29, 2012, so New Jersey hurricane deductibles did not apply. In Howell it still felled what the mayor estimated were thousands of trees, and Rep. Chris Smith said “nearly everyone had lost heat and power.” Crews hauled about 240,000 cubic yards of vegetative debris, and cleanup cost the township about $3.1 million, 90% of it repaid by FEMA.
“Sandy left about 240,000 cubic yards of tree debris in Howell.”
Tornadoes, wind and falling trees
The claims that actually happen here are wind and falling trees, and Howell has had tornadoes. In June 2017, two tornadoes with winds of about 75 mph touched down minutes apart, one at Fort Plains along Route 9 and one at Oak Glen Park, tearing metal roofing off a bank and toppling trees. On April 1, 2023, an EF-2 tornado with estimated winds of 120 mph crossed from Jackson into Howell near Aldrich Road. It snapped dozens of large trees, lifted the whole roof off one house, and drove a roof rafter into another.
Fire
Wildfire risk in most of Howell is low, but not zero. Howell is not in the Pinelands, but it has large pine and oak woods in Allaire State Park, the Bear Swamp Natural Area and around the reservoir. In October 2024, during a dry fall, a brush fire near Route 547 and Oak Glen Road closed both roads. If your home backs onto woods, keep brush and dead branches cleared.
Rain and flooding
Flooding here comes from rain and rivers, not the ocean. The Manasquan River and the North and South Branches of the Metedeconk River start in or run through Howell. During Hurricane Irene in August 2011, children in Mariners Cove, along the Manasquan, were taken from their homes by boat, and the township later bought out five lots there for $614,250 with hazard mitigation funds. In spring 2023, more than 6 inches of rain filled a basement on White Street in southern Howell up to the first floor. Howell has mapped flood hazard areas and has been in the National Flood Insurance Program since 1983. We recommend at least $25,000 of water backup coverage. Flood is a separate policy, so ask about it.
Home values and your dwelling limit
The U.S. Census Bureau puts the median value of an owner-occupied home in Howell at $507,200 (2020–2024 American Community Survey). Horse farms, large lots and newer custom homes can be worth far more. Rebuild cost is a different number from market value, so check your limit against our 2026 guideline of about $250 per square foot.
Check your Howell home in two minutes.
Three quick checks for any Howell home insurance policy.
1. Dwelling coverage guideline
Our 2026 starting point is about $250 per square foot. Custom finishes cost more.
2. Hurricane deductible
A percentage deductible applies to hurricane or wind damage, not to every claim.
3. Your flood zone
Look up your address on FEMA’s official flood map. Zones starting with A or V are high risk, and a lender will usually require flood insurance there. Homes outside those zones can still flood.
Check my flood zone on FEMA’s mapNot sure how to read it? Send us your address and we’ll tell you what it means for your Howell home.
What Howell homeowners should ask about.
- 01
Renovations and additions
Second stories, finished basements and extensions raise rebuild costs, but your dwelling limit often stays the same. Tell us about any work so coverage keeps up. We like to see about $250 per square foot as a starting point.
- 02
Oil tanks, wells and septic
Most of Howell is outside the public sewer service area, and many homes run on a private well and septic system. Older homes may also have a buried heating oil tank, which standard policies often exclude. Tell us what you have, and ask what your policy says about tank leaks, well pumps and septic backups.
- 03
Homes near the Manasquan and Metedeconk
Heavy rain can back up drains and overwhelm sump pumps. Keep at least $25,000 of water backup, and ask about a separate flood policy if you are near the Manasquan River, the Metedeconk branches or a local brook.
- 04
Basement apartments and ADUs
A basement apartment or accessory unit can make your home a multifamily dwelling to the carrier. You may need a landlord or dwelling fire policy (DP-3), and tenants may need renters insurance. Disclose the unit.
- 05
Acreage, horses, pools and guests
Large lots, barns, horses, pools and big gatherings all raise liability exposure. Ask about higher liability limits and an umbrella policy, and tell us about outbuildings, animals and temporary structures like a sukkah.
- 06
Jewelry, silver and Judaica
Standard policies often cap jewelry and silver theft at a few thousand dollars. Schedule jewelry, watches, silver Judaica and other valuables item by item with appraised values.
- 07
Vacation homes anywhere
Own a home at the shore, in Florida or elsewhere? We place home coverage in all 50 states through our carriers and partners.
“A well, a septic system and an oil tank are three things your carrier will want to know about.”
Stonebrook is an independent insurance agency.
We don’t work for one insurance company.
We work with more than 25 carriers and compare coverage for your Howell home. If another carrier fits your home better, we can place it there. Protecting New Jersey homes since 1982.
What clients say about Stonebrook.
“Super smooth getting my home reinsured through them. I emailed them my policy and they sent me a back a better one. Great experience working them”
“Rebecca gave such great service! Stonebrook is the best for both home and auto insurance in Lakewood, NJ.”
“This is the best insurance broker in Lakewood and surrounding areas they are honest and not pushy at all it was a pleasure talking to Nate they have the best rates that I have found thanks! Definitely recommend as top 5!”
Howell home insurance questions, answered.
What is an independent insurance agency?
An independent agency works with many insurance companies instead of one. Stonebrook is independent and compares more than 25 carriers for your home.
Is Howell considered coastal for home insurance?
Usually not, but it depends on the address. Most of Howell is 8 to 13 miles from the ocean, while Ramtown and the eastern edge are about 6 miles away, which some carriers count toward wind and hurricane rules. It depends on the carrier and the address.
Do I need flood insurance in Howell?
It is worth considering, because standard homeowners policies exclude flood. The Manasquan River flooded homes in Mariners Cove during Hurricane Irene, and heavy rain has flooded basements in other parts of town. Ask us whether flood coverage makes sense for your address.
How do I check if my address is in a flood zone?
Search your address on FEMA’s Flood Map Service Center at msc.fema.gov. It shows your flood zone on the current map. Homes outside a mapped zone can still flood, so ask us either way.
How much does home insurance cost in Howell?
It depends on your home, your carrier and your distance from the coast. For reference, NerdWallet put New Jersey’s average at $2,030 a year in 2026 for a sample policy with $600,000 of dwelling coverage. We compare more than 25 carriers to find the right price for your home.
What is a hurricane or wind deductible?
It is a separate, higher deductible for storm damage, usually a percentage of your dwelling limit instead of a flat dollar amount. A 2% deductible on a $500,000 home is $10,000. Check what triggers yours and how high it is.
Does my homeowners policy cover a neighbor’s tree falling on my house?
Usually, yes. Your own policy typically pays to repair your house, minus your deductible, no matter whose yard the tree grew in. The neighbor is generally responsible only if they were negligent, for example if they ignored a tree they knew was dead.
Does homeowners insurance cover my well or septic system?
Sometimes, for sudden damage. A well or septic system is often covered for named events like fire or a falling tree, but wear, gradual failure and clogs are usually excluded. Some carriers offer endorsements for equipment breakdown or underground service lines, so ask us what yours includes.
Is my sukkah covered?
Often, but check your policy. A sukkah is usually treated as an other structure or as personal property, and wind damage to it may be covered. Liability coverage applies to guests who get hurt, so make sure your limits are high enough.
Do I need to tell my insurance company about a basement apartment?
Yes. A separate unit that someone lives in can make your home a multifamily dwelling to the carrier. You may need a landlord or dwelling fire policy (DP-3), and tenants may need renters insurance. Disclose the unit to avoid problems at claim time.
How much dwelling coverage should I have in Howell?
As of 2026, we like to see about $250 per square foot of living space as a starting point, and more for custom finishes.
Can Stonebrook insure a vacation home outside New Jersey?
Yes. We place home coverage in all 50 states through our carriers and partners.
Get a free second opinion on your Howell policy.
- Upload your declarations page. It’s the summary page of your policy, usually 1–3 pages. A photo works.
- We check it against your Howell home. Dwelling limit, water backup, wind deductible, flood, liability and valuables.
- You get a plain answer. What’s fine, what’s missing, and whether one of our 25+ carriers can do better. No pressure.
Send us your policy.
We’ll look it over and get back to you with a plain answer.
Let’s make sure your Howell home is covered correctly.
Take 30 seconds to take the first step towards better coverage.
Get a quote.
Tell us what you need and we’ll take it from there.
Sources (28)
Facts on this page come from these public sources. Figures are as of the dates shown in the text.
- en.wikipedia.org · Howell Township, New Jersey
- en.wikipedia.org · Allaire State Park
- en.wikipedia.org · Allaire Village
- en.wikipedia.org · Manasquan Reservoir
- monmouthcountyparks.com · page
- monmouthcountyparks.com · page
- golfpass.com · 9132 howell park golf course
- en.wikipedia.org · Ardena, New Jersey
- en.wikipedia.org · Alexander Nevsky Cathedral, Howell
- www2.scc.rutgers.edu · farmingdaleb
- njjewishndev.timesofisrael.com · egg farmers look back with little nostalgia
- shorenewsnetwork.com · former howell stop shop to become massive kosher supermarket with free valet par
- censusreporter.org · 06000US3402533300 howell township monmouth county nj
- library.njcourts.gov · Howell2025HousingElement0625
- hip.cgph.net · howell emergency septic to sewer and water main program
- patch.com · howell twp federal assistance for superstorm sandy cleanup costs to reach 27m
- amp.insurancejournal.com · 27
- mesonet.agron.iastate.edu · 202304051202 KPHI NOUS41 PNSPHI
- abc7ny.com · new jersey storm damage nj howell township jackson
- shorenewsnetwork.com · brush fire breaks out in howell township prompting road closures
- patch.com · relief in sight for mariners cove residents
- newjersey.news12.com · howell residents still feeling effects of hurricane irene 34868818
- patch.com · weekend flooding damages basement house howell
- webarchive.library.unt.edu · cis
- weather.gov · sandyreport
- nerdwallet.com · homeowners insurance nj
- consumerreports.org · when a tree falls who pays for the damage
- msc.fema.gov
Photo credits
- “Barn in Howell, NJ” by Freeholdman12, CC BY-SA 4.0. Source: Wikimedia Commons
- “Howell (Township) NYPL1603098” by F. W. Beers, cartographer (New York Public Library), Public domain. Source: Wikimedia Commons
- “Manasquan Reservoir, NJ panorama from visitors center, June 2025” by Mr. Matté, CC BY-SA 4.0. Source: Wikimedia Commons
- “Pine Creek Railroad” by DCwom, Public domain. Source: Wikimedia Commons
- “Manasquan River at Howell Park Golf Course” by Jonathan Schilling, CC BY-SA 4.0. Source: Wikimedia Commons
- “Ardena, NJ Baptist Church, Aug. 2025” by Mr. Matté, CC BY-SA 4.0. Source: Wikimedia Commons


